
Central Texas Real Estate Market: Why Some Homes Sell While Others Sit
October 2026 | Pine & Paul Real Estate · 3-minute read
The Central Texas housing market is changing, and buyers are becoming more selective.
Across Austin, Round Rock, Georgetown, Pflugerville, Cedar Park, and Leander, we're seeing a growing distinction between homes that attract attention and those that struggle to generate interest.
The three factors we're watching most closely are price, move-in-ready condition, and location.
1. The market is moving slower
September's housing data tells an important story.
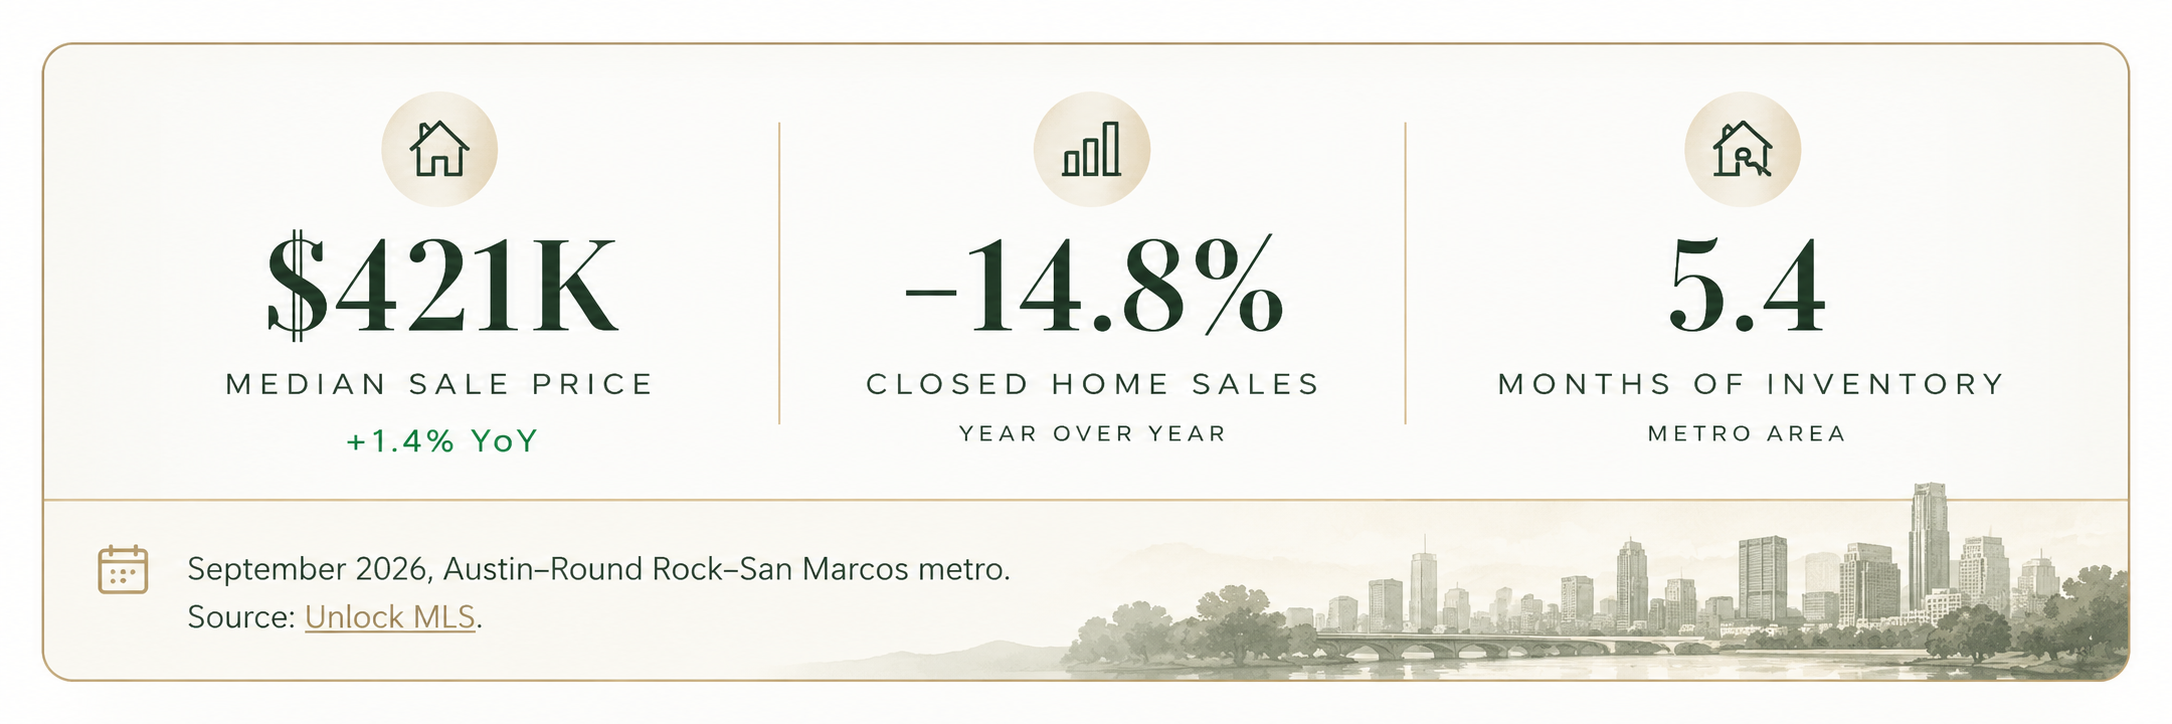
Closed sales declined nearly 15% compared with September 2025, yet the median price increased slightly.
That tells us something important: a slower market doesn't necessarily mean every home is losing value.
Buyers are still purchasing homes, but affordability and the competition between available properties are making the right pricing strategy increasingly important.
2. Buyers want homes that feel finished
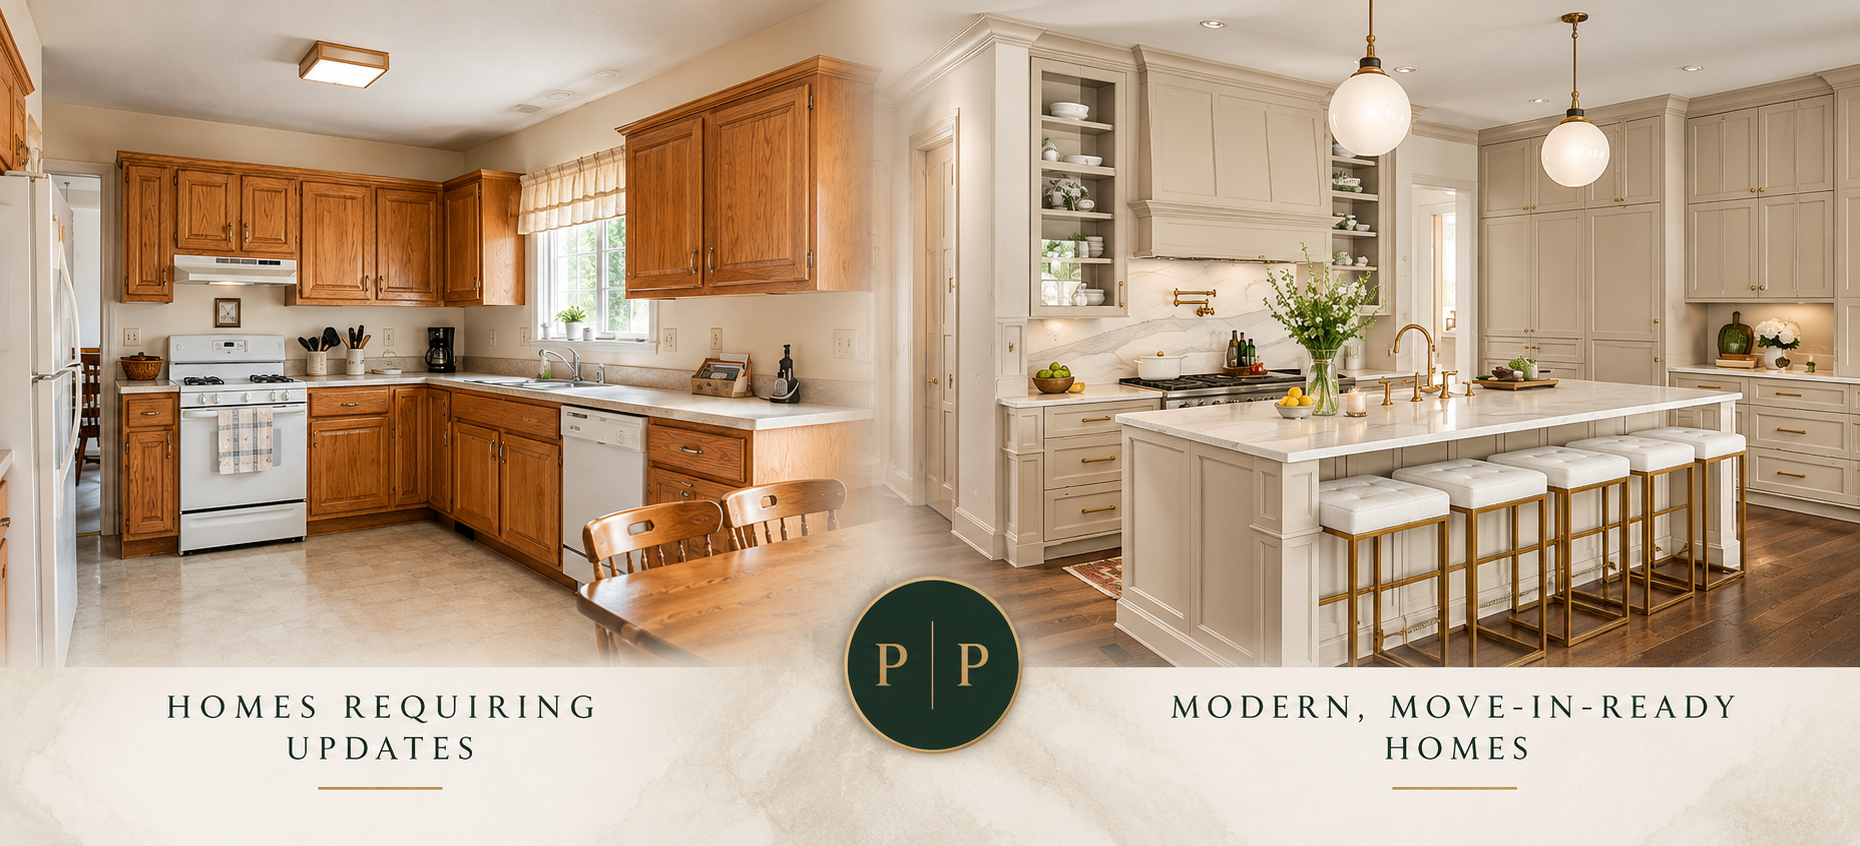
One of the clearest trends we're observing through our work with Central Texas buyers is a preference for homes that don't require immediate renovations.
Modern kitchens, updated bathrooms, cohesive flooring, and thoughtful finishes can make a meaningful difference in how buyers perceive a property.
Buyers aren't just considering the purchase price. They're thinking about the additional cost, time, and inconvenience of making improvements after closing.
For sellers, this doesn't mean every home needs a full remodel. Strategic improvements and presentation often matter more than expensive upgrades that don't align with the neighborhood.
3. Location is about lifestyle, not just an address
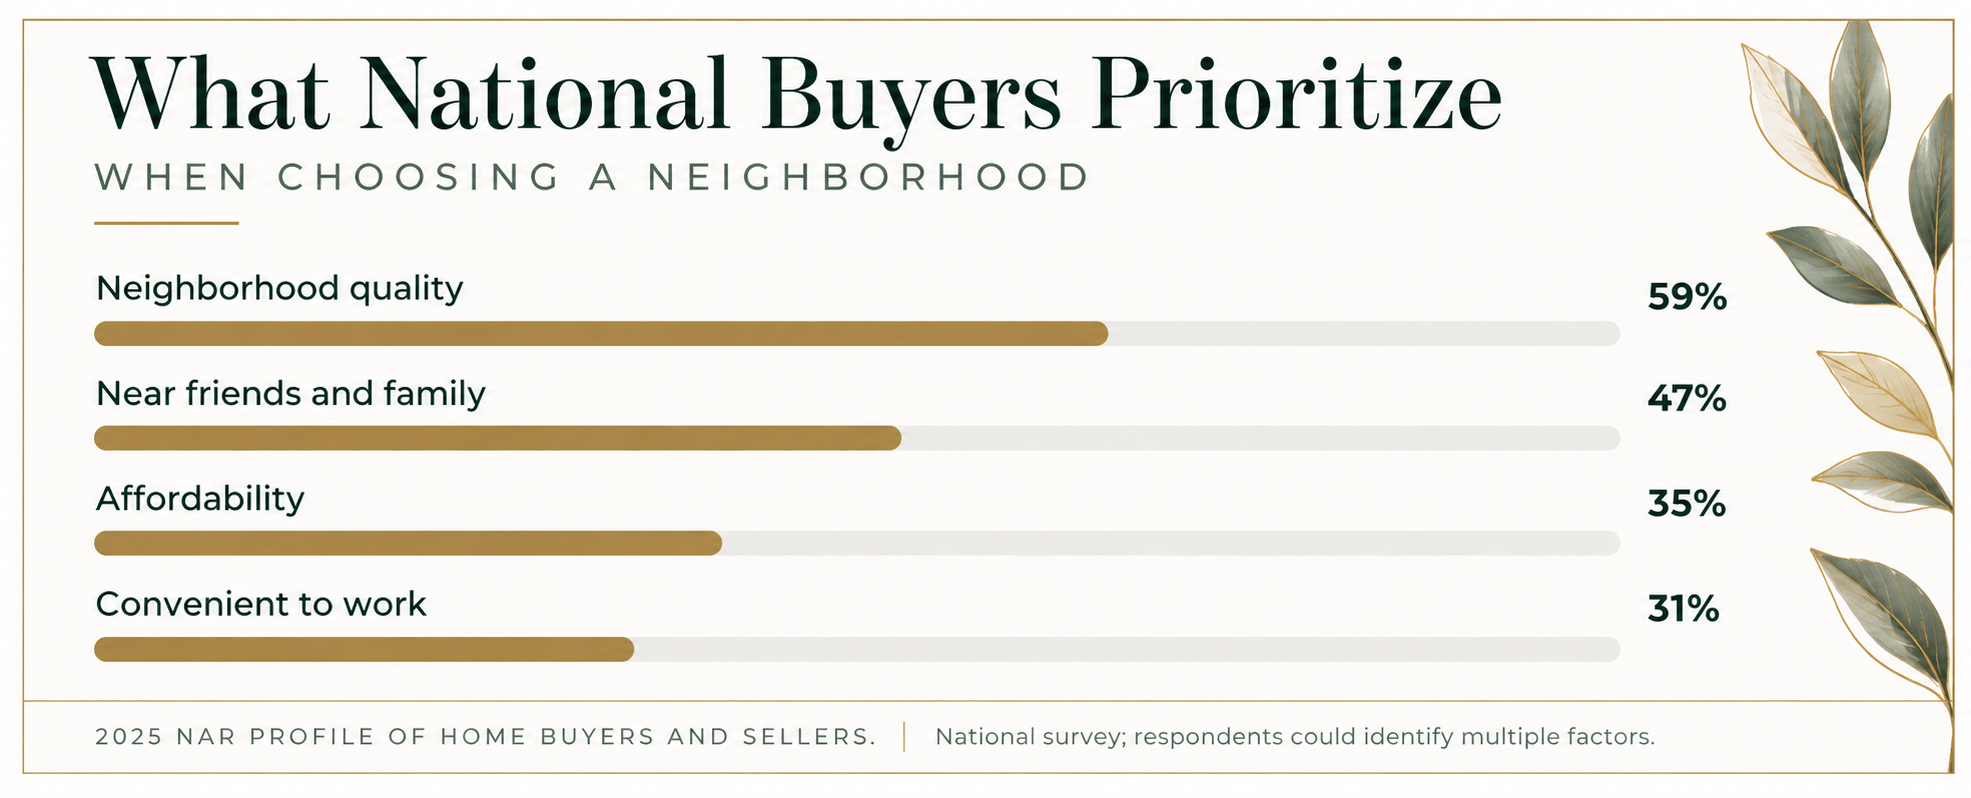
Location has always mattered, but we're seeing buyers pay close attention to how a home fits their everyday lives.
Commute routes, shopping, dining, neighborhood amenities, nearby development, and convenience all play a role.
A beautifully updated home may still struggle if its location doesn't meet buyers' needs. Meanwhile, a well-located home with fewer upgrades may attract interest because of what the surrounding area offers.
4. What does this mean for sellers?
Today's market rewards preparation and realistic expectations.
Homes that are priced appropriately, presented professionally, and positioned against their actual competition have a stronger foundation for attracting buyers.
At Pine & Paul, we believe selling successfully starts well before the listing goes live. Understanding the neighborhood, identifying worthwhile improvements, and developing a deliberate pricing and marketing strategy can help a home stand out.
The Pine & Paul perspective
Central Texas isn't experiencing one uniform housing market.
What's happening in Georgetown may look very different from Round Rock or North Austin. Even homes within the same neighborhood can attract different levels of interest based on their condition, floor plan, location, and price.
For buyers, that creates opportunities to evaluate properties more carefully and negotiate strategically.
For sellers, it means preparation and positioning have become essential.
At Pine & Paul Real Estate, we help our clients understand those differences and make informed decisions based on their specific property and goals.
Sources & Market Research
1. Unlock MLS — September 2026 Central Texas Housing Report Regional median home prices, closed sales, and housing inventory. View Report
2. National Association of REALTORS® — 2025 Profile of Home Buyers and Sellers Buyer preferences, neighborhood priorities, and reasons for purchasing new construction. View Research
3. Zillow Research — 2026 Consumer Housing Trends Report National homebuyer preferences, affordability considerations, and housing trends. View Research
4. Pine & Paul Real Estate — Central Texas Market Observations Insights based on firsthand buyer consultations, property showings, listing activity, and local market analysis throughout Central Texas.
Disclaimer: Market statistics reflect the reporting periods and geographic areas identified in their respective sources. National buyer trends may not represent every Central Texas neighborhood. Local conditions vary by location, property type, price range, and condition.
Portable Mortgages: Could You Take Your Mortgage Rate With You When You Move?
If you bought or refinanced a home when mortgage rates were historically low, you’ve probably asked yourself a version of this question at least once:
Why would I sell my house and give up my low mortgage rate?
It’s a fair question, and it’s one of the biggest reasons many homeowners who might otherwise move are staying put.
That mortgage “lock-in effect” has become one of the defining forces in today’s housing market, and Washington is now looking at a potential solution: portable mortgages.
If portable mortgages eventually become widely available, they could reshape the Austin housing market, Central Texas home prices, housing inventory, and how homeowners think about selling one home and buying the next.
What Is a Portable Mortgage?
A portable mortgage is essentially a mortgage that can move with the homeowner, kind of like a cell phone number instead of a landline.
Under the traditional system, when you sell your home, the mortgage attached to that property is paid off at closing. If you buy another home, you get a new mortgage at whatever rates and terms are available at that time.
A portable mortgage works differently. Instead of leaving your mortgage behind when you sell, a qualifying homeowner could potentially transfer the remaining balance, interest rate, and loan terms to the next property.
For homeowners sitting on a low mortgage rate, that distinction could be a very big deal.
Where Do Portable Mortgages Actually Stand Right Now?
Headlines have blurred together several developments surrounding portable mortgages, so it’s important to separate the idea from what homeowners can actually do today.
Portable mortgages are being discussed at the federal level as a potential way to address the mortgage lock-in effect. Federal housing officials have publicly discussed evaluating the concept, and proposed legislation has sought to create a framework for portable mortgages involving Fannie Mae and Freddie Mac.
But portable mortgages are not currently a broadly available benefit that allows homeowners to simply move an existing conventional mortgage from one property to another.
That distinction matters.
Homeowners with 2%, 3%, or 4% mortgage rates should not assume they can carry those rates to their next home today. Any future portable mortgage program would likely have eligibility requirements, lending guidelines, property requirements, and other limitations.
Why Are Portable Mortgages Being Discussed?
One of the biggest challenges in today’s housing market is something economists call the mortgage lock-in effect, which is just a fancy way of saying people are staying put even when they’d rather move.
Imagine a homeowner bought a house a few years ago and has a 3.25% mortgage. Their family has grown and they’d like a bigger home.
The problem isn’t necessarily selling their current house. It’s financing the next one.
Trading a 3.25% mortgage for a significantly higher rate can dramatically change the monthly payment on the next home. For some homeowners, that difference is enough to delay moving altogether.
Portable mortgages are designed to potentially remove some of that barrier.
How Could Portable Mortgages Affect the Austin Real Estate Market?
This is where the idea becomes especially interesting for homeowners in Austin, Round Rock, Georgetown, Cedar Park, Leander, Pflugerville, Liberty Hill, Hutto, and the surrounding Central Texas real estate market.
Central Texas experienced extraordinary homebuying activity during the pandemic-era housing boom, when mortgage rates reached historic lows.
Many homeowners who bought or refinanced during that period are now sitting on mortgage rates they would understandably hate to give up.
If mortgage portability eventually allows some of those homeowners to move without completely losing the benefit of their existing rate, it could change several parts of the Central Texas housing market.
More Homeowners Could Decide to Sell
Some homeowners aren’t staying in their homes because the house is perfect. They’re staying because the mortgage is.
Take away some of the financial penalty associated with moving, and homeowners who have been postponing a sale may finally decide to list.
That could add housing inventory throughout Austin and surrounding Central Texas communities.
Buyers Could Have More Homes to Choose From — But Potentially More Competition Too
More sellers generally means more options for buyers.
But there’s another side to the equation.
Most homeowners who sell their primary residence also need somewhere else to live. If portable mortgages encourage more homeowners to sell, many of those sellers could immediately become buyers.
That means portability could potentially increase housing supply and buyer demand at the same time.
Could Portable Mortgages Increase Home Prices?
Possibly, and this is one of the more interesting parts of the entire idea.
If homeowners can carry a much lower mortgage rate into their next purchase, their buying power could increase.
Someone carrying part of a mortgage at 3% may be able to comfortably afford a home that would be considerably more expensive to finance entirely at current mortgage rates.
If portability brings previously sidelined buyers back into the market, demand for certain homes could increase along with inventory.
So portable mortgages would not automatically mean cheaper housing.
They could improve homeowner mobility without necessarily solving housing affordability.
What Happens If the Next House Costs More?
This is one of the biggest questions homeowners have about portable mortgages.
Imagine a homeowner owes $350,000 on a mortgage at 3.25% but wants to purchase a $600,000 home.
Even under a portable mortgage structure, the existing $350,000 loan would not simply become a $600,000 mortgage at 3.25%.
The homeowner would still need to cover the difference between the transferable mortgage amount and the purchase price through their equity, additional cash, or potentially additional financing at current market rates.
Exactly how that additional financing would work would depend on the rules of any future portable mortgage program.
That is why the details matter so much.
Portable Mortgage vs. Assumable Mortgage
Portable mortgages and assumable mortgages sound similar, but they work in almost opposite directions.
With an assumable mortgage, the buyer takes over the seller’s existing mortgage, subject to the applicable loan and qualification requirements.
With a portable mortgage, the concept is that the seller takes their existing mortgage with them and applies it toward another qualifying property.
Certain FHA, VA, and USDA mortgages may already be assumable under qualifying circumstances.
Portable conventional mortgages, however, are not currently broadly available in the United States.
The easiest way to remember the difference is:
Assumable mortgage = the buyer takes the mortgage.
Portable mortgage = the seller takes the mortgage with them.
Why Portable Mortgages Could Matter So Much in Central Texas
The Austin and Central Texas real estate market is particularly interesting when discussing mortgage portability because of what happened here during the pandemic-era housing boom.
Thousands of homeowners purchased or refinanced properties while mortgage rates were historically low.
At the same time, many Central Texas homeowners have accumulated significant equity in their properties.
That has created an unusual situation.
Some homeowners have the equity and financial ability to move, but replacing their existing low-rate mortgage with a significantly higher-rate loan changes the economics of that decision.
A homeowner may want another bedroom, a larger backyard, a different school district, a shorter commute, or simply a different home.
But when they compare their current mortgage payment with what the payment could be on their next home, staying put can suddenly look much more attractive.
Portable mortgages are aimed directly at that problem.
What Should Austin Homeowners Do Right Now?
Nothing changes about your existing mortgage simply because portable mortgages are being discussed.
Homeowners should also be skeptical of headlines suggesting they can already transfer their existing mortgage rate to another house.
For most conventional homeowners, that option does not currently exist.
There is also no guarantee that a future portable mortgage program would allow every homeowner with a low mortgage rate to transfer it.
Any final program could include significant restrictions involving loan type, borrower qualification, property value, loan-to-value ratios, additional financing, or the properties themselves.
Still, portable mortgages are worth watching closely.
For the Austin and Central Texas real estate market, anything that reduces the mortgage lock-in effect could influence how many homeowners decide to sell, how many buyers enter the market, housing inventory, purchasing power, and potentially home values.
At Pine & Paul Real Estate, we track changes like these because real estate decisions aren’t made in a vacuum.
Interest rates, financing options, housing inventory, new development, property values, and local market conditions all factor into whether it makes sense to buy, sell, invest, or stay put.
We serve buyers, sellers, and real estate investors throughout Austin, Round Rock, Georgetown, Cedar Park, Leander, Pflugerville, Liberty Hill, Hutto, and the greater Central Texas real estate market.
We’re also following the portable mortgage discussion and what it could mean locally on Selling Austin.
Wondering what your current mortgage rate and equity position could mean for your next move? Contact Pine & Paul Real Estate for a no-obligation conversation about your options.
Portable Mortgage FAQ
What is a portable mortgage?
A portable mortgage would allow a qualifying homeowner to transfer certain terms of an existing mortgage, potentially including the remaining balance and interest rate, to another qualifying property instead of paying off the entire loan and obtaining an entirely new mortgage.
Are portable mortgages available in the United States in 2026?
Portable mortgages are being discussed and proposed at the federal level, but homeowners cannot currently assume that an existing conventional mortgage can simply be transferred to another property.
Can I transfer my 3% mortgage to another house?
Not currently in the way being contemplated by portable mortgage proposals. Do not assume that an existing low-rate mortgage can automatically be transferred to another home.
What’s the difference between a portable mortgage and an assumable mortgage?
An assumable mortgage allows an eligible buyer to take over the seller’s existing mortgage, subject to applicable requirements. A portable mortgage would allow an eligible homeowner to move their mortgage from the property they’re selling to the property they’re buying.
Would portable mortgages help the Austin housing market?
Potentially. Portable mortgages could encourage some homeowners with low mortgage rates to sell, which could add inventory. However, many of those sellers would also become buyers, potentially increasing demand at the same time.
Would portable mortgages lower home prices?
Not necessarily. Additional inventory could benefit buyers, but increased purchasing power and additional buyer demand could also support home prices. Mortgage portability is primarily intended to address homeowner mobility rather than housing affordability by itself.
What happens if my new house costs more than my current mortgage?
A portable mortgage would not necessarily allow the entire new purchase to be financed at the homeowner’s existing interest rate. The homeowner could need additional cash, equity, or financing to cover the difference. The exact structure would depend on the rules of any future program.
Should I wait for portable mortgages before buying a home in Austin?
There is no guarantee when, how, or whether portable mortgages will become broadly available. A home purchase should be evaluated using today’s home prices, mortgage options, available inventory, personal finances, and long-term goals rather than relying on a proposed future financing option.
Where can I learn more about the Austin and Central Texas real estate market?
Pine & Paul Real Estate provides local real estate information, market analysis, and guidance for buyers, sellers, and investors throughout Austin, Round Rock, Georgetown, Cedar Park, Leander, Pflugerville, Liberty Hill, Hutto, and surrounding Central Texas communities.
New Construction vs. Resale Homes in Austin: Which Is Better for Buyers?
Short version: if your priority is the lowest monthly payment you can get right now and you don't mind living a little further out, new construction is probably going to win, thanks to how aggressive builder incentives have gotten. If you care more about a settled neighborhood, mature trees, and a location that won't shift under you, resale is usually the smarter play. But "probably" and "usually" aren't good enough when you're talking about the biggest purchase most people ever make, so let's actually walk through it.
I get asked this question almost every week, and it's rarely as simple as "new is better" or "resale is better." It really comes down to what you're optimizing for, and whether you've actually run the numbers or just eyeballed the price tags.
Why this question matters more than it used to
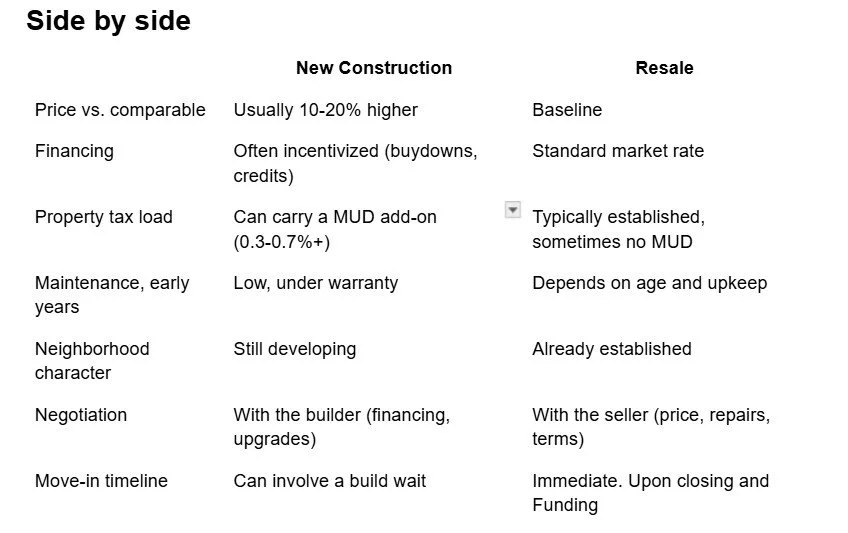
A few years ago this was almost a moot point. Resale inventory was scarce, homes sold in days, and builders had waitlists. That's flipped. New construction now makes up close to a third of all active listings in the Austin metro, which tells you everything about how much has changed. Resale sellers who locked in 3% rates during the pandemic aren't in a hurry to give that up, so a lot of them just... aren't selling. Builders, on the other hand, keep building no matter what rates do. So they're sitting on inventory, and they need to move it.
That's why you're seeing incentive packages everywhere right now: rate buydowns, closing cost credits, $10,000 to $30,000 in design allowances, even the occasional "4.99% rate!" banner outside a model home (sometimes lower for the first year or two). It's real money. But it's also, in my experience, the part buyers get most dazzled by without looking at what's underneath it.
The case for new construction
The honest upside here is real. Everything's new (HVAC, plumbing, roof, windows, insulation), which usually means a handful of boring, maintenance-free years while everything's still under warranty. You're not inheriting someone else's decades-old decisions about the kitchen layout. And if you buy early enough in the build process, you actually get to pick some of those decisions yourself.
Then there's the financing. A builder buydown can shave real money off your monthly payment, sometimes more than an equivalent price cut would. That's not a gimmick. It's genuinely one of the better tools in this market.
Here's what I wish more buyers asked before they got excited about a model home, though: what's the base price actually included? Because "homes from the $400s" rarely means the home you end up wanting. Lot premiums, upgraded flooring, extra bedrooms, a better elevation, it all adds up fast, and a to-be-built home can drift a long way from that first number by the time you're at the closing table. An already-finished inventory home is usually a cleaner comparison, since the price is set and the builder's often more motivated to move it.
And then there's the thing nobody at the sales office volunteers: a lot of these newer communities sit inside a MUD, a Municipal Utility District. That adds somewhere around 0.3% to 0.7% onto your property tax rate, permanently, to pay off the bonds that funded the roads and water lines. It's not a one-time fee. It rides along with your tax bill for years, sometimes decades. I bring this up constantly with clients because it's exactly the kind of thing that gets buried under a shiny rate buydown, and the buydown expires while the MUD tax doesn't.
The case for resale
What resale gives you that no builder can manufacture is time: mature trees, a neighborhood that's already settled into whatever it's going to be, an actual sense of place. You can drive the streets and see how people take care of their homes instead of trying to picture it from a rendering of a park that might get built in three years.
You also get to see the home's actual history: past repairs, disclosures, whether the roof's already been replaced, whether someone already sank money into the kitchen. That's information a new build simply can't give you yet, because it doesn't have a past.
And negotiating with a person is a different animal than negotiating with a builder. Sellers can move on price, repairs, closing costs, timeline. There's more room to shape a deal around what actually matters to you, whether that's cash at closing or getting them to fix the foundation issue your inspector flagged.
Which brings me to the thing I say to almost every resale buyer: don't skip the option period inspection to win a bidding war. I know the temptation is real in a competitive situation, but Central Texas clay soil is not forgiving, and foundation problems are common enough here that this isn't a hypothetical. Get the inspection. Every time.
The number that actually decides it
Here's the exercise I walk almost every buyer through, and it's the one step most people skip: stop comparing sale prices and start comparing what you'll actually pay every month. That means mortgage payment at your real interest rate (not the teaser rate that expires in year three), property taxes including any MUD add-on, insurance, and HOA dues.
Two homes priced identically on paper can land in very different places once you do this. A buydown might make new construction cheaper for the first couple of years, and then the rate resets while the MUD tax keeps going, and the math flips. I've seen it go both ways. That's exactly why I run this comparison for clients before they commit to either option, instead of letting a listing price make the decision for them.
Questions I get asked a lot
Is it cheaper to buy new construction or resale in Austin?
Honestly, it depends on the specific homes and the specific financing on the table. New construction can come with an incentive that lowers your effective rate; resale can come with a seller willing to cover closing costs or drop the price. The only fair comparison is the full monthly number: mortgage, taxes, insurance, HOA. Not the price on the sign.
Are property taxes actually higher on new construction in Austin?
Not just because it's new, but a lot of newer communities sit inside a MUD, which tacks on roughly 0.3-0.7% to the effective tax rate to cover infrastructure bonds. That can run for years. Always ask whether a specific community is in a MUD before you compare its tax bill to a resale home's.
Can you actually negotiate the price on a new build?
Sometimes, but builders would usually rather hand you a financing incentive or upgrade credit than cut the price outright. It protects their comps for the rest of the community. How much room there is depends a lot on how much inventory that builder still has to move.
Do I need my own agent if I'm buying new construction?
Yes. The person in the sales office is friendly, but they work for the builder. Having your own agent means someone's actually looking out for your side: the price, the incentives, the contract, and whether a comparable resale might be the better deal. Loop your agent in before you tour communities, since some builders have rules about representation that get messy if you show up alone first.
Should I still get an inspection on a brand-new home?
Yes, every time. New homes can absolutely have construction defects. Different trades, different subcontractors, and mistakes happen even with good builders. An inspector works for you, not the builder, whether the house is 30 days old or 30 years old.
Is new construction a better investment than resale around here?
Not automatically. Location, tax burden, lot, and what gets built around the property over the next few years matter more than whether the paint is fresh. A well-located resale in an established area can easily outperform a new build sitting in a community that's still filling in.
What's the real difference between a to-be-built home and an inventory home?
A to-be-built home lets you pick finishes and layout, but you're on the builder's timeline and exposed to price creep on upgrades along the way. An inventory home is already finished, selections already made, price already set, and often the better negotiated deal, since the builder's carrying costs on a house that's just sitting there.
Want to run your specific numbers?
If you're weighing new construction against resale anywhere in Round Rock, Pflugerville, Cedar Park, Georgetown, or greater Austin, I'd rather sit down and show you the real month-one and year-five cost on the actual homes you're considering than let a builder's flyer or a listing price make the call for you. That's the part of this I can do that most agents can't: running the tax side of it with the same license I use to protest tax appraisals, not just guessing at it.
Reach out and let's run the comparison together.
About the author: Ariel and Jeff Pine of Pine & Paul Real Estate and Pine & Paul Property Tax Consulting LLC, is a licensed real estate agent and property tax consultant (Agent #1898231) serving the Round Rock, Pflugerville, Cedar Park, Leander, Georgetown, Liberty Hill and greater Austin market.